|
More information about the proposed changes to CRA can be found on the AHTCC Regulatory Issues Resource Center and on the AHTCC’s blog. The AHTCC has also developed talking points to support members and industry partners in their advocacy efforts. As a reminder, the deadline to submit comments to the OCC and FDIC is tonight at 11:59pm ET.
Today, Bloomberg News also published an article about the CRA proposal, “Trump-Backed Housing Rule Could Undercut Effort to Lower Costs,” which features the AHTCC’s survey results. AHTCC CEO Emily Cadik is quoted as saying, “The proposal would have a disproportionate impact on rural housing investments, and we think it would remove the strong incentive that currently exists for a number of banks to invest in affordable housing.”
The Federal Reserve is not participating in the OCC and FDIC’s proposed rulemaking, and Federal Reserve Board Governor Michael Barr was also quoted as saying, “Community banks are really important all over the country, but especially in small towns and rural areas. So if you’re not careful about how you look at the levels of tiering in a proposal, you might end up reducing the amount of capital going into affordable housing in rural areas and small towns, in particular, and we want to make sure we don’t do that.”
The AHTCC also joined an ACTION Campaign sign-on letter expressing the affordable housing community’s concerns about the potential impact of the proposal on Housing Credit investment.
The Importance of CRA for the Housing Credit
CRA is central to supporting Housing Credit demand. Banks provide roughly 75 to 80 percent of Housing Credit equity, and at least 71 percent is considered CRA-motivated. The CRA investment test in particular has helped create a deep, competitive, and efficient market for the Housing Credit, which is especially important in light of the historic expansion of the program as part of One Big, Beautiful Bill.
The Impact of the CRA Proposed Rule on Housing Credit Investment
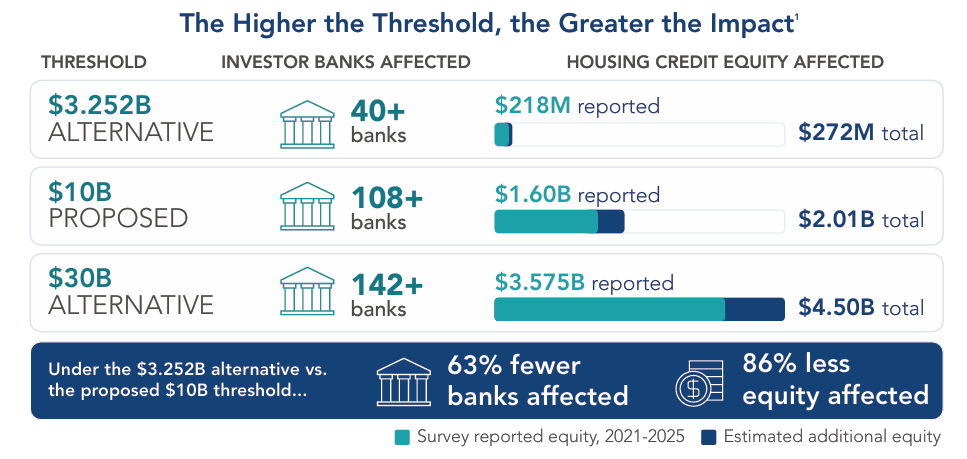
Removing the investment test requirement for banks under the $10 billion threshold would remove an incentive for a significant number of banks to invest in the Housing Credit. To assess the potential impact of the proposed changes, the AHTCC surveyed Housing Credit syndicators to identify bank investors that would be affected by the proposal and quantify their investments. The survey data identified at least 108 banks below the $10 billion proposed threshold, representing approximately $1.6 billion in Housing Credit equity over the five-year survey period. Extrapolating these results to the full Housing Credit market, the AHTCC estimates that approximately $2 billion in Housing Credit equity investment over those five years came from banks that would be affected by the proposed threshold increase.
The Impact of the CRA Proposed Rule on Rural Areas
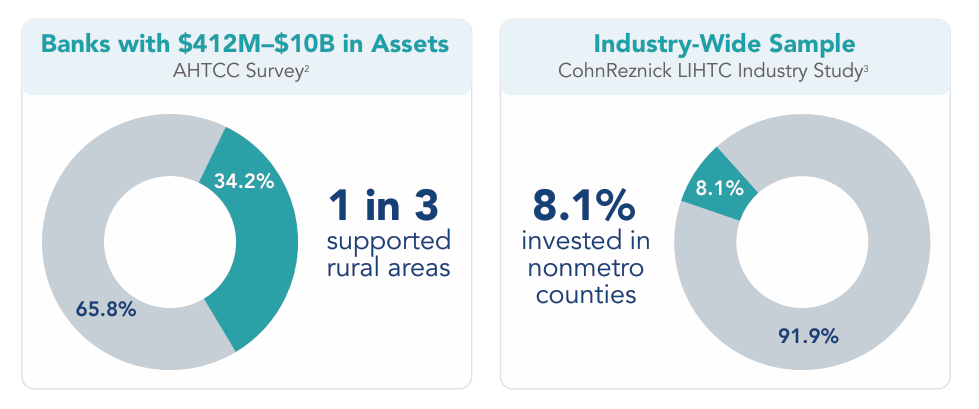
Banks under the $10 billion threshold play a particularly important role in financing affordable housing in rural communities. AHTCC survey data show that approximately one-third of Housing Credit equity investments from banks under $10 billion in assets supported rural markets, indicating that banks in this asset range play an outsized role in investing in rural communities. By comparison, 8.1 percent of Housing Credit equity in a CohnReznick industry-wide sample was invested in nonmetro counties, a proxy for rural and small-town markets. |

Comments are closed.